St. George & Washington County Home Loans | The Mortgage Rebel
Red-rock views. Real-life budgets. Whether you’re buying your first home, using your VA benefits, or weighing a Southern Utah investment, start with financing that fits how you’ll actually use the property.
Meet Kristopher “Kris” Matyas: an Army veteran with more than 25 years in mortgage lending, VA-loan expertise, and firsthand experience owning a short-term rental in Washington, Utah. Get a local owner’s perspective and clear financing guidance for your next move.
Kristopher “Kris” Matyas · Utah mortgage broker · U.S. Army veteran
Founder, The Mortgage Rebel · NMLS #864775
Mortgage services through Barrett Financial Group, LLC · NMLS #181106
Southern Utah home financing, without the runaround.
Serving St. George, Washington, Hurricane, Ivins, Santa Clara, La Verkin, Leeds, and surrounding Washington County communities—including buyers exploring Desert Color, Sand Hollow, Sienna Hills, and Escondido. Your property, income, and intended use shape the financing conversation.
Run the Numbers Before You Buy.
Estimate your monthly payment or see how seller concessions could help lower your initial mortgage payments.
Calculators provide estimates, not approvals or loan offers. Temporary buydowns reduce payments for a limited period; they do not permanently reduce your mortgage note rate. Program eligibility and funding requirements vary.
VA home loans
Explore your earned benefit, available entitlement, and potential no-down-payment financing for an eligible home you’ll occupy.
Explore Utah VA loans →First-time buyers
Start with a comfortable full monthly payment, funds for closing, and reserves. Compare conventional, FHA, eligible USDA, or VA options; assistance programs have their own requirements.
Compare loan programs →Conventional & FHA
Compare down payment, mortgage insurance, closing costs, and qualification requirements. FHA financing includes mortgage insurance; the right choice depends on your complete profile.
USDA, where eligible
USDA financing may fit eligible borrowers buying a primary home in a qualifying rural area. Both household income and the exact property location need review; eligibility is not countywide.
Second homes & investments
Tell us how much you’ll use the home and whether you plan to rent it. Conventional or available investment/DSCR programs have different occupancy, reserve, property, and income rules.
Refinancing & cash out
Review your existing loan, equity, costs, timeline, and goals. A refinance replaces debt; cash out increases the amount owed and is subject to eligibility and equity requirements.
One property. Three very different financing conversations.
Primary residence
The home you intend to live in. Owner-occupant options may include conventional, FHA, VA, and USDA financing when their requirements are met.
Second home
A home for your personal use during part of the year. Lenders review occupancy, location, property type, and any rental or management arrangement. A vacation destination alone does not make a property eligible.
Investment property
A property purchased to generate rental income. Underwriting may consider income, reserves, rental cash flow, and the property’s eligibility. An Airbnb business plan should be disclosed before choosing a loan.
Describe your intended use accurately. Loan approval, city rental permission, and HOA approval are separate decisions; one does not establish the others.
Veteran Buying in Southern Utah? Work With a Fellow Veteran!
YOUR SERVICE. YOUR NEXT CHAPTER.
- U.S. Army
- U.S. Navy
- U.S. Air Force
- U.S. Marine Corps
- U.S. Space Force
- U.S. Coast Guard
Original Mortgage Rebel service-inspired artwork, not official military seals. No Department of Defense, military service, or VA endorsement is implied.
Kris brings an Army veteran’s perspective and mortgage industry experience since 1998. We’ll review your Certificate of Eligibility, remaining entitlement, income, credit, and plans for the home.
- Potential zero down: available to qualifying borrowers, subject to entitlement, lender requirements, and appraised value. Closing costs can still apply.
- No monthly PMI: VA-backed loans do not require monthly mortgage insurance.
- Credit is reviewed: VA does not set a universal minimum credit score; individual lenders set their own credit standards and review the overall file.
- Occupancy matters: VA purchase loans are for a home you intend to occupy, not a property bought solely as a vacation rental or Airbnb investment.
VA purchase and jumbo loans in Washington County
Buying a home you intend to occupy in St. George, Washington, Hurricane or another Washington County community? Kris Matyas can help review your Certificate of Eligibility, entitlement, and lender requirements for income, credit and the property. VA purchase financing requires qualifying occupancy; it is not for a home purchased solely as a vacation rental or second home.
With full entitlement, VA does not impose a county loan limit. Higher-balance financing—often called a VA jumbo loan—may be available with no down payment for eligible borrowers, subject to lender approval and a supporting appraisal. This is not unlimited borrowing power. If entitlement is already in use, remaining entitlement and the property’s county limit can affect the required down payment. Closing costs and any applicable funding fee are separate considerations.
Source: VA entitlement & loan limits, checked October 15, 2026. Explore our Utah VA home loans, VA benefits guide and mortgage payment calculator.
Verify your funding-fee status
Veterans receiving VA disability compensation for a service-connected disability are generally exempt from the VA funding fee. A 0% disability rating alone does not establish an exemption. Other exemptions may apply. Your exemption status must be verified through VA.
Additional categories can include eligible compensation recipients paid retirement or active-duty pay instead, surviving spouses receiving DIC, qualifying pre-discharge determinations, and active-duty Purple Heart recipients who meet VA requirements.
Read VA benefits & requirements →Source: VA purchase loans and VA funding-fee guidance. Mortgage Rebel and Barrett Financial Group are independent of VA and the military.
Buying a St. George Airbnb? Understand the Market Before You Invest.
A beautiful property still needs a workable operating budget and an exit plan. Compare competing rentals, new construction, recent resale transactions, and address-specific rental permissions before relying on projected income.
“As a short-term-rental property owner in Washington, Utah, I’ve experienced firsthand how increased competition and changing market conditions can affect rental income and resale opportunities. I believe buyers should carefully evaluate the numbers before purchasing a vacation-rental investment.”
— Kris Matyas, The Mortgage Rebel
Three counts. Three different markets.
Research checked October 15, 2026. Reporting periods and geographic coverage differ; these figures should not be added together or treated as a forecast.
Residential homes for sale
Washington County’s July 2026 MLS report lists 2,093 homes in inventory and 67 days on market until sale. This covers residential listings, not just vacation rentals.
July 2026 local MLS report ↗Active vacation rentals
AirDNA’s Saint George market reports 1,263 active listings through September 2026. These are rental listings—not properties listed for sale—and are not a Washington County total.
AirDNA market & definitions ↗STR properties for sale
No verified, current MLS count of STR-eligible properties for sale is included here. Request a dated, deduplicated search with exact boundaries, listing status, and documented rental eligibility.
Read the methodology, definitions & source notes ↓
New homes compete with resales
Desert Color’s developer currently markets multiple builders, resort lots, and vacation-rental products. Compare a resale against available new homes, incentives, amenity charges, completion schedules, and future phases—not only yesterday’s comparable sales.
Developer’s vacation-rental offerings ↗ · Community & builder information ↗
An active developer offering is not a count of completed homes or countywide building starts. Community results vary.
Underwrite the slow months, too
- Request monthly booking history, owner-blocked nights, cancellations, and actual operating statements.
- Budget HOA dues, management, insurance suited to rental use, taxes, utilities, cleaning, repairs, furnishings, and replacement reserves.
- Stress-test lower occupancy, lower nightly revenue, and a longer resale timeline.
- Compare properties with similar bedrooms, amenities, management, and rental permission. Gross revenue is not cash flow.
Washington County housing prices and inventory
The latest county report listed on the local Board’s statistics page when checked October 15, 2026 covers July 2026, with data current August 10. Median sales price was $540,000, up 2.9% from July 2025; inventory was 2,093, up 4.7%. The report shows 5.3 months of supply and 67 days on market until sale. This is a dated residential MLS snapshot, not live October inventory or a count of STR-eligible homes for sale. Prices do not account for seller concessions.
Washington County MLS · July 2026 · Report index
Saint George vacation-rental supply and performance
AirDNA’s October 13, 2026 update covers September 2026: 1,263 active rentals, 52% occupancy and $47,800 average annual revenue. Its year-over-year comparisons report active listings down 31%, occupancy up 1.8% and annual revenue per listing up 23%. Average daily rate was $272, down 8.5%, while revenue per available rental was $143, down 5.9%.
These are source-reported changes for AirDNA’s Saint George market, not Washington County totals or a forecast for your property. Revenue is before host expenses. Changing listing composition and different metrics can produce different trends; these figures alone do not establish overbuilding. Compare the specific property’s operating history and competing rentals.
AirDNA · September 2026 data; updated October 13. Definitions and qualifications remain in the expandable sources below.
Compare communities at the property level
Desert Color

Confirm the exact product and phase, rental designation, amenity access, and ongoing costs. The developer markets both residential and vacation-rental options.
Escondido at Sienna Hills
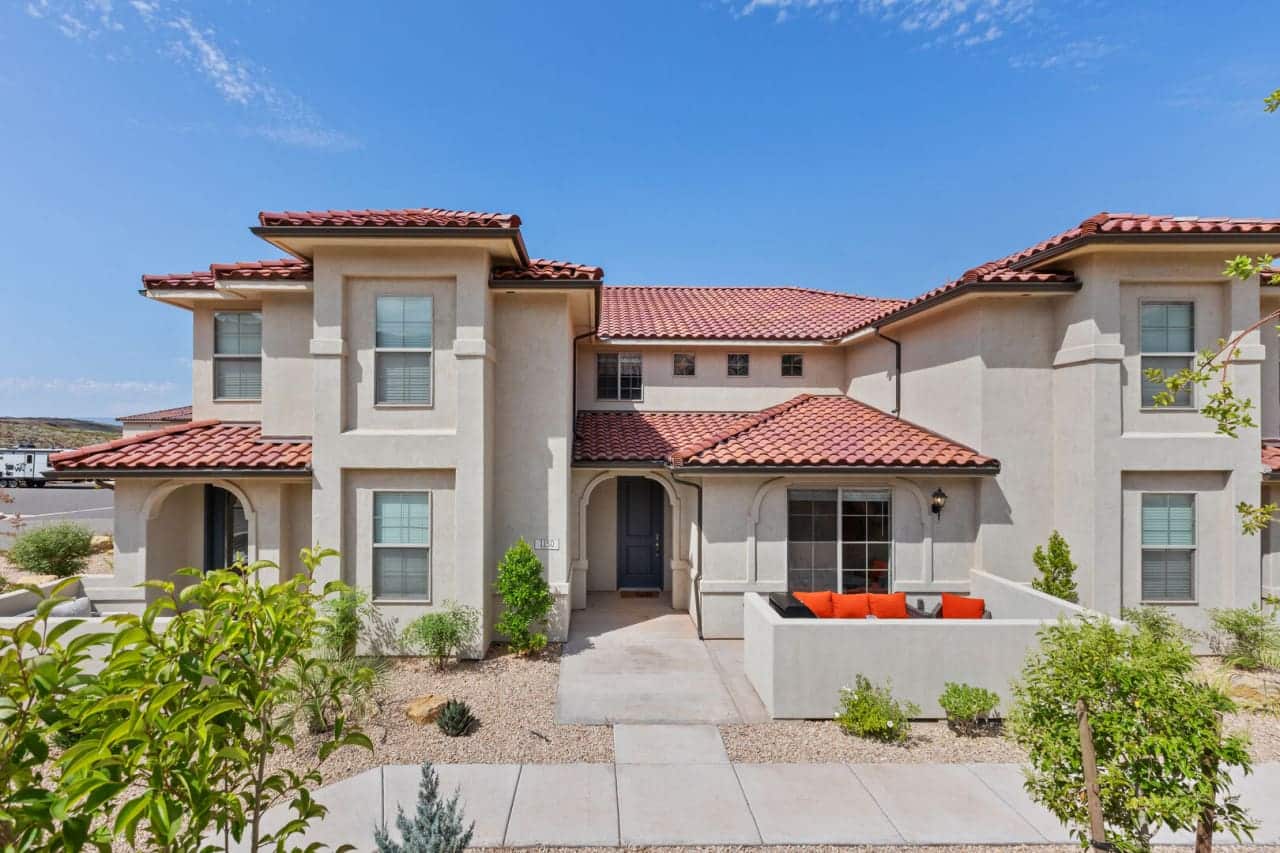
Washington City Code 3-2-13 requires a separate STR business license for each property and says licenses do not transfer between people or structures. Confirm new-owner licensing before relying on the seller’s bookings.
For a Washington City property, verify the unit’s approved use, HOA documents, current license requirements, and comparable rental history.
Sand Hollow & Coral Canyon

Check the exact subdivision and governing city. A familiar neighborhood or resort name does not establish permission for every address.
Are short-term rentals allowed everywhere? No.
Verify zoning and any required rental license with the governing city or Washington County for an unincorporated parcel. Review HOA restrictions, parking, occupancy limits, inspections, and whether a new owner needs a new approval. A seller’s past bookings are not proof that you can legally continue them.
St. George licensing & approved-area resources ↗ · Washington City STR licensing rules ↗ · Hurricane vacation-rental rules ↗
Hurricane states that rentals in approved Recreational Resort areas still need a license and annual fire inspections. Confirm current, property-specific requirements directly with the jurisdiction before committing.
Explore Vacation Rental Property Management in Washington County
Management is one part of an investment plan. Explore Stay Propr’s property management services as one local resource, then compare service scope, fees, owner responsibilities and property eligibility with other providers.
Relationship disclosure: Kris Matyas has an existing business relationship with Stay Propr, the vacation-rental property management company he uses. Stay Propr is separate from Mortgage Rebel; Mortgage Rebel does not own or operate it. This is an optional example, not an exclusive recommendation or a condition of mortgage services. Management does not establish STR licensing, HOA permission or a guarantee of income.
Considering a Southern Utah Investment Property? Let’s Run the Financing Numbers.
Live Where Others Vacation: Explore Southern Utah
Water & weekends
Explore boating at Sand Hollow Reservoir, boat and personal-watercraft/WaveRunner rental options, and recreation at Quail Creek. Check operators, availability, launch conditions, and park rules before going.
Sand Hollow park information ↗Quail Creek park information ↗
Sand Hollow boat & Sea-Doo rentals ↗
Park rental resources ↗
Check current operator pricing and availability. Confirm launch conditions and boat-storage arrangements directly; floating launch docks do not establish overnight-slip availability.
Red rock & trails
Enjoy hiking in Snow Canyon, mountain biking and cycling on designated trails, or OHV/UTV adventures near Sand Hollow. Match the route to your experience and check heat, closures, and permitted uses.
Explore Snow Canyon ↗St. George parks, trails & bike-route map ↗
Use the city map to locate Pioneer Park/Dixie Rock and nearby trail access. Check park alerts, trail conditions, parking, and heat before heading out.
Adventure Your Way
Local shooting ranges and recreational shooting opportunities require checking the specific facility or land manager’s access rules, hours, and current restrictions. Washington County’s Shooting Sports Park is one place to begin your research.
Red Cliffs Range: visitor rules & current hours ↗Sand Hollow & Sand Mountain OHV information ↗
Local UTV/ATV rental options ↗
Confirm range access and rules with the facility. Check OHV training, permits, designated routes, and rental conditions before riding.
Planning a visit or a move? Explore our Living in St. George, Utah guide for Washington County boating, trails, local recreation, communities and a place to stay while you explore.
Straight answers to Southern Utah mortgage questions.
Who can help me get a VA loan in St. George?
Kris Matyas, a Utah mortgage broker and U.S. Army veteran working through Barrett Financial Group, can help you review VA eligibility, entitlement, lender requirements, and financing options. Start with a consultation or our Utah VA home loan resource.
Can a larger Washington County home qualify for zero-down VA financing?
Potentially. With full entitlement, VA does not impose a county loan limit. Higher-balance VA financing still requires lender approval, qualifying occupancy and a supporting appraisal. Remaining entitlement can affect the down payment when a prior VA loan is still charged to your entitlement. Closing costs and any applicable funding fee are separate.
Can I buy with no down payment?
Possibly. VA and eligible USDA options can offer no-down-payment financing for qualifying borrowers and properties. Appraisal, entitlement, income, credit, and lender requirements still apply. No down payment does not mean no closing costs.
What credit score is required for a VA loan?
VA does not establish one universal minimum credit score. Lenders set their own standards and also review income, debts, residual income, and credit history. Ask Kris to review your situation rather than relying on a single advertised cutoff.
Can I finance a second home in Southern Utah?
Yes, if you and the property meet the selected program’s requirements. Explain your intended personal use and any rental plans before applying. A property operated primarily as a rental may require investment-property financing.
Can I use a VA loan to purchase an Airbnb?
Not for a property purchased solely as a vacation rental or investment. VA purchase financing requires qualifying occupancy. An owner-occupied property with additional units can involve different rules; discuss the exact plan with the lender and confirm local rental restrictions.
What should I know before purchasing a St. George vacation rental?
Verify rental permission, license requirements, HOA rules, actual operating history, complete expenses, competing supply, and an exit plan. Separate gross revenue from net cash flow and test a lower-income scenario before you commit.
Are short-term rentals allowed throughout Washington County?
No. Rules depend on the exact parcel, governing jurisdiction, zoning, and HOA documents. Confirm permitted use and licensing directly with the city—or the county for unincorporated property. A marketing description is not a rental permit.
What mortgage options are available to first-time buyers?
Depending on eligibility, conventional, FHA, VA, or USDA loans may be options. Compare the down payment, mortgage insurance, cash needed at closing, full monthly payment, and available assistance. Review our Loan Programs page and payment calculator.
Contact Kris about St. George financing.
Tell me what you’re planning. I’ll help you understand the financing questions to ask before you buy, refinance, or invest.
Call 801-638-0507 · Email Kris
Ready to apply?
The mortgage application opens in Barrett Financial’s separate application portal. Its privacy practices and application process are separate from this website contact form.
Apply Now / Get PreapprovedSources, scope & information date
Washington City licensing reference: Code 3-2-13, compilation 2026 S-22, checked October 15, 2026. Confirm the exact property and current requirements with the city.
Occupancy, revenue & methodology
AirDNA reports 52% occupancy and $47,800 average annual revenue for its Saint George market through September 2026, updated October 13. Occupancy is booked nights divided by available nights over the trailing 12 months; revenue includes nightly charges and guest fees before host expenses. Active listings were available or booked in the trailing year, deduplicated across Airbnb, Vrbo, and Booking.com. These modeled market figures are not audited property income, net profit, year-round occupancy, or a guarantee.
The July MLS report was current August 10, 2026. The Board’s methodology excludes for-sale-by-owner transactions, includes some but not all new construction, and is not seasonally adjusted. Its price metrics do not account for seller concessions. Different sources and dates can produce different counts.
- Information reviewed October 15, 2026. Market snapshots use the reporting periods shown, not live counts. Verify current terms, property eligibility, and rules before making a decision.
- Washington County Board of REALTORS® housing statistics: July 2026 county report, current August 10, 2026. Residential MLS data; not a vacation-rental resale count.
- AirDNA Saint George overview: through September 2026; updated October 13. Platform-defined market, trailing-year rental activity and estimated performance.
- Desert Color developer: current community and builder offerings, not independent investment-performance data.
- VA home loans; USDA Guaranteed Loan Program. City licensing, Utah State Parks, and photograph credits are linked alongside the relevant sections.
Educational information, not investment, tax, or legal advice. No approval, income, appreciation, or resale outcome is promised. Program availability and terms vary by lender, borrower, and property.
Optional visit attribution is off unless you choose Allow.
Privacy details