Utah has been in a buyer’s market for nearly all of 2026, and that changes the playbook for both buyers and sellers this fall. Buyers hold real negotiating power right now, while sellers must list against today’s slower-moving demand rather than 2025’s frenzy. In the Utah MLS daily snapshot, October 21, 2026, the average home sits 69 days before going under contract — enough time to negotiate, inspect, and counter without a bidding war. That 69-day timeline continues the sustained buyer’s advantage Utah has held throughout the year, stretching past September’s 65-day trend as part of the same year-long balance. Buyers can use this window to schedule pre-winter inspections and negotiate concessions while the market remains in their favor.
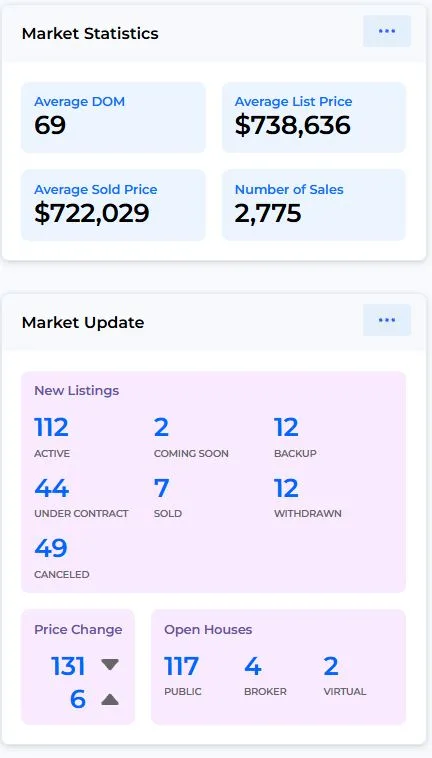
The Utah MLS daily snapshot, October 21, 2026 confirms the buyer’s edge: 69 days average time on market, $738,636 average list price, $722,029 average sold price, and 2,775 sales. That 69-day timeline is what buyers and sellers are negotiating against right now, and it has already stretched past September’s 65-day trend.
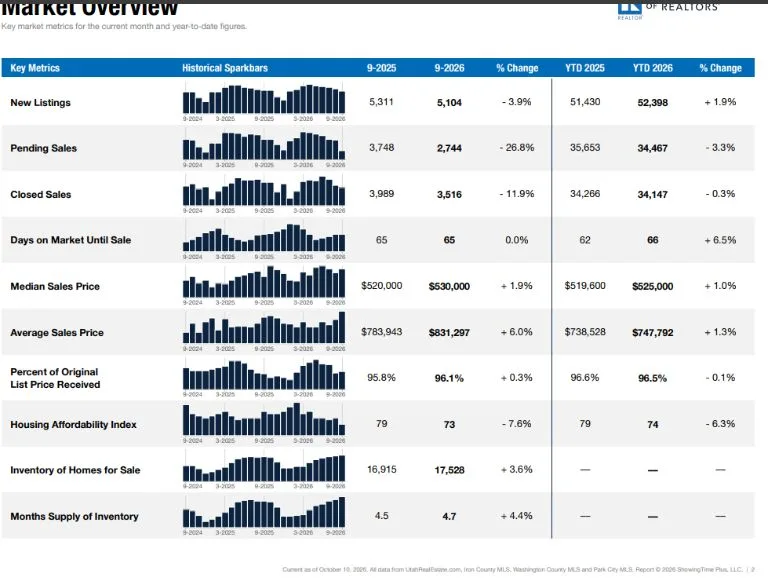
September 2026, Utah Association of Realtors monthly report adds the trend context: the median sales price sits at $530,000, with 17,528 active listings (a 4.7-month supply). These are the trailing-month figures behind today’s faster-moving snapshot, and they matter for gauging momentum — not for pricing your October offer.
This 2026 update is designed to help you secure a home or sell your property before the Wasatch Front is covered in snow, which traditionally makes inspections for roofs, sprinklers, and landscaping nearly impossible. Here is what you need to know to win in the current landscape.
Sustained Advantage: Why 2026 Has Been a Buyer’s Market All Year
This isn’t a recent development — Utah has been in a buyer’s market for nearly the entire year. In the September 2026, Utah Association of Realtors monthly report, inventory increased by 3.6% to 17,528 homes for sale, while closed sales fell by 11.9% year-over-year. That surplus has kept the market tilted toward buyers month after month, and today’s 69-day snapshot is simply the continuation of that year-long balance.
A “buyer’s market” is traditionally defined by inventory levels. In the September 2026, Utah Association of Realtors monthly report, Utah held a 4.7-month supply of inventory, a 4.4% increase from last year. That means if no new homes were listed, it would take nearly five months to sell everything currently on the market. For buyers, this translates to more choice and, more importantly, less pressure to waive inspections or overpay.
For sellers, this prolonged shift requires a move away from “aspirational pricing.” Properties that are not priced precisely against recent comparable sales are being bypassed by a smaller, more discerning pool of buyers who are highly sensitive to monthly payment costs.
A local MLS snapshot — a specific Utah area, October 21, 2026 illustrates the point: 112 active new listings, with only a handful sold in the same window. That micro-market example is not statewide data — but it shows how thinly buyers are spread even in busy pockets of the state.
65 Days and Counting: Understanding Modern Market Timelines
The September trend tells the timeline story, but October has already moved past it. In the September 2026, Utah Association of Realtors monthly report, homes sat for a median of 65 days on market (DOM) before going under contract — a 6.5% increase year-to-date from the frenzy of 2024 and 2025.
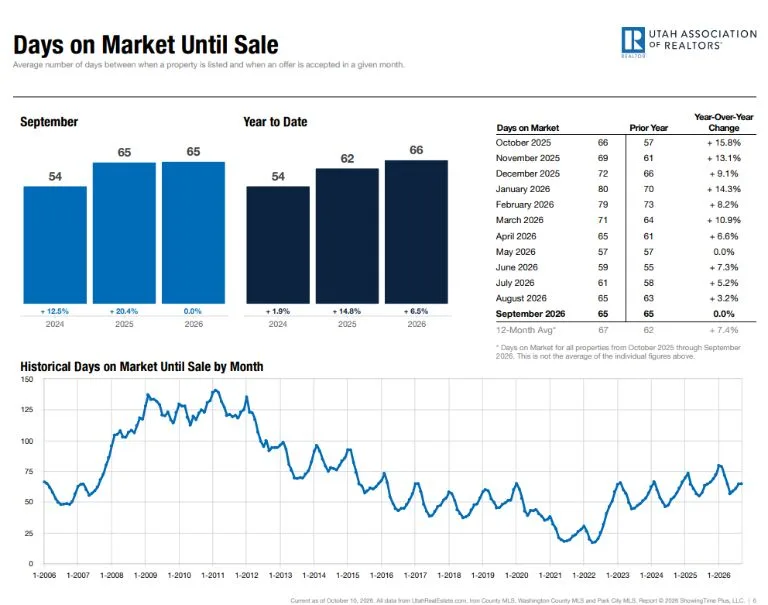
For buyers, that longer timeline is a gift. It eliminates the “bid-or-lose” pressure that often leads to buyer’s remorse. You now have the time to visit a property multiple times, bring in a contractor for a specialized quote, and negotiate terms without a dozen competing offers breathing down your neck. In the current Utah MLS daily snapshot, October 21, 2026, that window has stretched even further to 69 days. For sellers, however, this means the first 30 days are no longer the “sold or failed” period; patience is now a requirement of the listing process.
Success Check: You should now see that a home sitting for 45 days is no longer a “problem property,” but rather a standard listing in the 2026 environment.
The Art of the Concession: How Sellers are Closing the Gap
The days of intense bidding wars are officially in the rearview mirror. In the September 2026, Utah Association of Realtors monthly report, sellers are receiving 96.1% of their original list price. That nearly 4% gap between asking and closing price signals that concessions have become the primary currency of the 2026 market.
In a “higher for longer” rate environment, the most valuable concession isn’t always a lower sales price—it’s a seller-funded rate buydown. By contributing 2-3% of the purchase price toward the buyer’s closing costs, a seller can effectively drop a buyer’s interest rate from 7.40% to 5.40% for the first year. This “2-1 buydown” strategy lets sellers hold their home’s value while making the monthly payment affordable for the buyer.
Success Check: You should be able to identify whether a listing agent/seller is open to a rate buydown versus a simple price reduction in your initial inquiry.
Beat the Snow: The Critical Importance of Pre-Winter Inspections
In Utah, the “market window” closes effectively when the first major snowstorm arrives. For buyers currently under contract or searching, the next few weeks are the last opportunity to perform a truly comprehensive home inspection. Once the ground and roof are covered in snow, some of a home’s most expensive components become invisible.
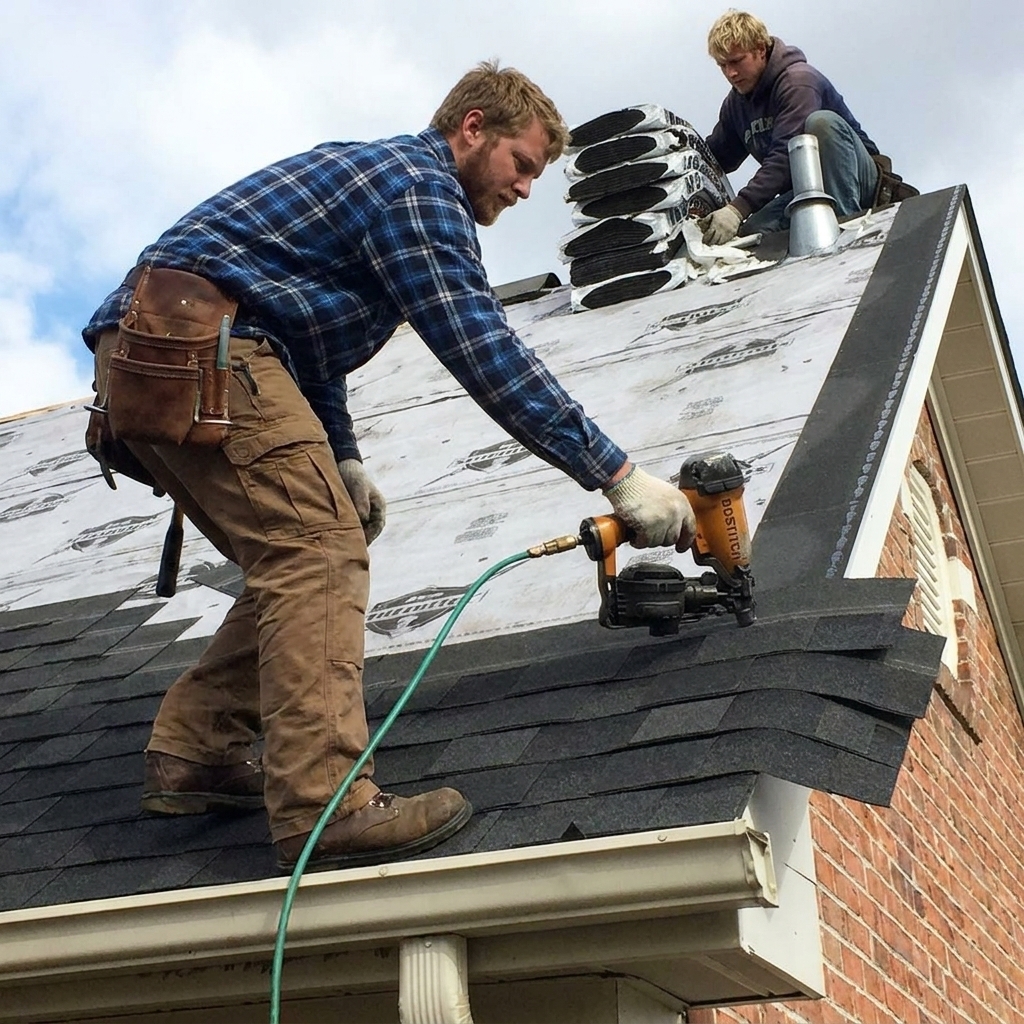
A standard Utah home inspection in late October should prioritize three “snow-sensitive” areas:
-
The Sprinkler System: Irrigation lines must be tested and properly winterized before the ground freezes. An inspector cannot find cracked lines or faulty valves under a foot of snow.
-
The Roof and Gutters: Snow hides missing shingles and prevents an inspector from checking for “ice dam” risks. You need to verify the integrity of the roof while the surface is still clear.
-
Grading and Landscaping: Proper drainage is what keeps a basement dry during the spring melt. If the yard is covered in snow, you cannot see if the ground slopes toward the foundation.
Success Check: You should have a completed inspection report that explicitly confirms the condition of the sprinkler zones and roof before the first snow forecast.
Waiting for Lower Rates Could Cost You
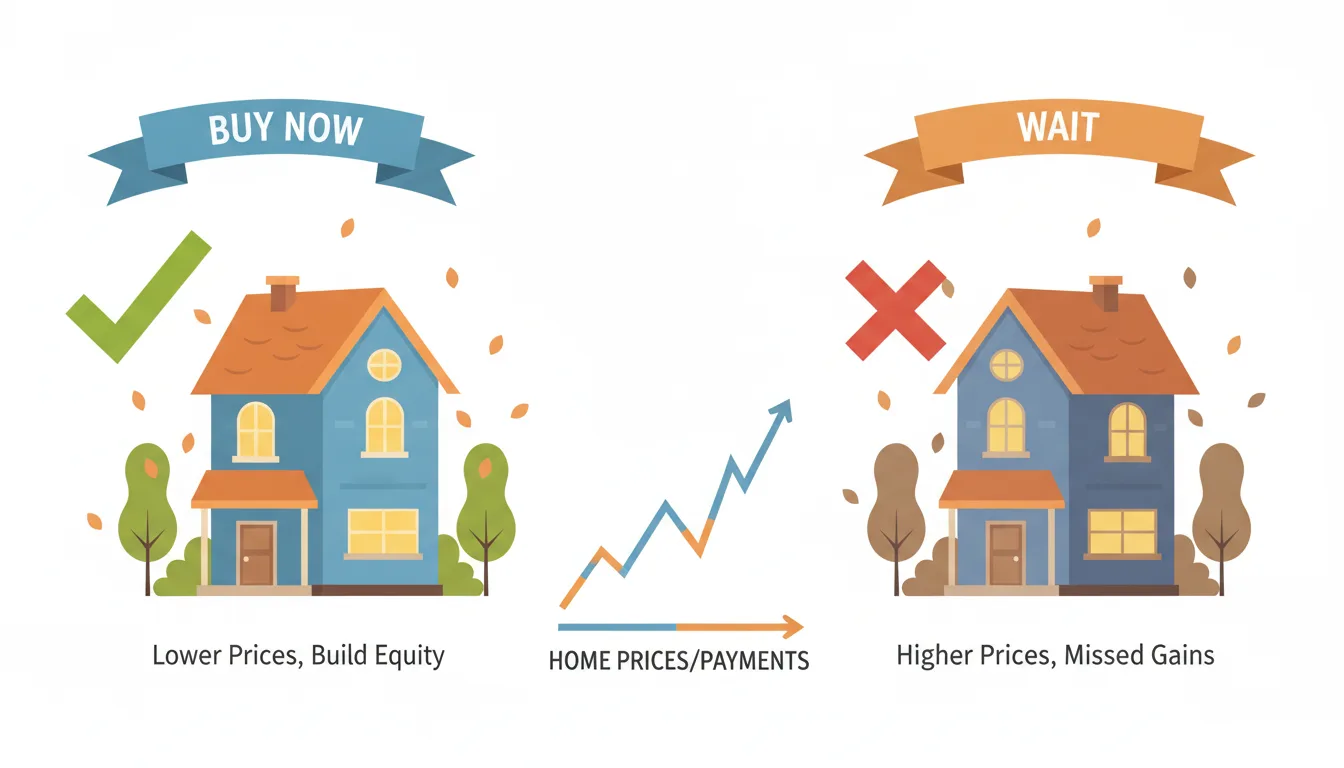
Sidelined buyers waiting for lower rates create the opportunity for the buyers acting now. Because fewer buyers are competing today, those who act in this 2026 buyer’s market hold negotiating leverage they won’t have once rates fall and demand returns.
No rate cuts are on the forecast. The Federal Reserve is expected to hold rates at its October 27–28 meeting and raise them again in December, according to nearly all economists polled by Reuters on October 20, 2026 (Reuters). The next move is up, not down.
When rates do eventually fall, the dynamics flip. Sidelined buyers flood back into the market, competition returns, and prices climb — today’s buyer-market discount disappears as demand outpaces the inventory that has kept Utah balanced all year.
Utah home prices also trend upward year over year. Waiting until next year likely means a higher purchase price on top of everything else, which can offset any savings from a slightly lower rate.
|
Buy Now |
Wait |
|
|---|---|---|
|
Purchase price |
$500,000 |
$525,000 |
|
Down payment (20%) |
$100,000 |
$105,000 |
|
Loan amount |
$400,000 |
$420,000 |
|
Interest rate |
7.375% |
6.875% |
|
APR |
7.426% |
6.922% |
|
Monthly principal & interest |
$2,762.70 |
$2,759.10 |
Waiting saved $3.60/month — and cost $25,000 more for the house, plus $5,000 more down.
Taxes and insurance are on top of these principal-and-interest figures and vary by county.
Hypothetical illustration for educational purposes only — not a rate quote, not an offer or commitment to lend. Assumes 30-year fixed-rate mortgage, 20% down payment, 740+ credit score, zero discount points, $1,995 lender fees, no mortgage insurance. Principal and interest only; taxes and insurance not included. Actual rates, APR, and payments depend on credit profile, loan program, and market conditions at time of application.
Interest Rate Realities: Why Waiting for 2027 Might Not Pay Off
One of the most common questions in the Utah market today is whether to “wait for rates to drop.” However, current economic indicators suggest a “higher for longer” reality. As of October 20, 2026, the average top-tier 30-year fixed mortgage rate sits at 7.40% (Mortgage News Daily), the third-lowest level in more than three weeks. While this is a slight dip from recent weeks, it remains far above the sub-3% lows seen during the pandemic era.
For Utah buyers, waiting for a 1% drop in rates may be offset by the continued rise in home values. If you buy now at 7.40% and rates eventually drop, you can refinance. If you wait and prices rise another 5%, you’ve lost your negotiation leverage in a buyer’s market.
Success Check: You should be able to calculate your monthly payment at the current 7.40% rate and confirm it fits your budget before proceeding.
How to Negotiate: Winning Strategies for Both Parties
In a buyer’s market, negotiation is not about one side winning and the other losing; it’s about finding the “sweet spot” where a deal can actually close despite high interest rates.
For Buyers: Focus on the “Net Effective Cost.” Instead of asking for a $10,000+ price drop, ask for a $10,000+ seller credit to buy down your interest rate OR to obtain a 1-0, 1-1, 2-1 or 3-2-1 temporary buydown. This often saves you more on your monthly payment than a price reduction would, while allowing the seller to keep their “Sold Price” high for the neighborhood comps. *Not all mortgage lenders offer these temporary rate buydowns. Verify with your lender during the pre-approval process. They can provide the amount required as each property will require different amounts.
For Sellers: Be proactive with your inspection. Offer a “pre-inspected” home and show that you’ve already handled the pre-winter sprinkler blowouts. In a market with 17,528 competing listings (September 2026, Utah Association of Realtors monthly report), being the “easy” home to buy is a massive competitive advantage.
Success Check: You should be able to present a counter-offer that addresses both the monthly payment (for the buyer) and the net proceeds (for the seller).
Ready to see your actual numbers?
Call or text 801-638-0507, or hit the button below — takes about 60 seconds.
Kristopher Matyas | The Mortgage Rebel | Barrett Financial Group, NMLS #864775. Not a rate quote or commitment to lend.
Leave a Reply